How Much Does a Surety Bond Cost in India?
Contractors working on government tenders, road construction, construction contracts, and infrastructure projects may struggle to obtain a financial guarantee. The traditional method of using a bank guarantee is not always feasible, as it might involve locking away large sums of money as collateral. It could create problems regarding paying salaries, buying materials, and other day-to-day costs.
A surety bond is an alternative that helps meet contractual obligations and use working capital more efficiently. But at what price? The cost depends on the bond amount, the project’s characteristics, the contractor’s financial state, and many other factors. Consider these factors when choosing surety bond insurance.
What factors affect the cost of a surety bond in India?
There is no standard cost for the surety bond in India. This is because the insurer evaluates each case individually, and two contractors requesting a similar bond amount may be offered different premium rates. Market premiums for indicative purposes usually range from 0.5% to 3% of the bond value, but rates may fall outside this range depending on the level of risk and the policy terms.
1. Type of Surety Bond
Different types of surety bond cover different risks. A bid surety bond provides security during tendering, while a performance surety bond protects the project owner if the contractor fails to fulfil its responsibilities. A mobilization advance bond covers risks arising from advance payments. The premium rate depends on the bond type, coverage amount, and risk involved.
2. Bond Amount and Project Value
The higher the bond amount, the higher the premium amount. For example, a ₹10 lakh bond at 1% has a premium of ₹10,000, while a ₹50 lakh bond has a premium of ₹50,000 at the same rate.
3. Project Duration
The longer the bond period, the higher the cost, as the insurer is exposed to risk for longer. Confirm the bond’s validity period and factor in any extension or renewal in case of delays in completing the construction project.
4. Contractor’s Financial Strength
The insurer may examine the financial strength of the company, including turnover, the extent of debts, cash flows, and credit history of the contractor. If a contractor has sound financial records and minimal debts, better terms may be obtained from the insurers.
5. Previous Project Experience
A proven track record of timely completion on other projects may increase the insurer’s confidence. New contractors may provide information about their past experiences in other projects.
6. Insurer’s Risk Assessment
Every insurer has its own way of underwriting insurance. Therefore, careful consideration should be taken while comparing quotations, taking into account premiums, coverages, exclusions, conditions, and extra charges.
How is the surety bond premium calculated?
Estimating the premium is fairly simple when you know the bond amount and the premium rate offered by the insurance company.
The formula for the same can be represented as follows:
Surety bond premium = Bond amount × Premium rate
For example, if a contractor requires a surety bond of ₹40 lakhs at a premium rate of 1.5%.
The calculation becomes as follows:
- Bond amount: ₹40,00,000
- Premium rate: 1.5%
- Estimated premium: ₹40,00,000 × 1.5% = ₹60,000
Hence, the estimated premium is ₹60,000, excluding the applicable GST and stamp duty, if any. Please note that the premium rate does not necessarily remain the same across contractors and bonds and is confirmed by the insurer after reviewing the application documents.
Surety Bond vs Bank Guarantee: Cost and Financial Impact
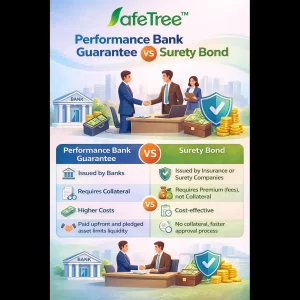
Surety bond and bank guarantee are two tools that may help ensure financial security for the project owner. However, these tools are not identical and may affect the contractor’s financial position differently. In a bank guarantee, the bank assures payment to the beneficiary if the guarantee’s conditions are met. The bank may require a cash margin, a fixed deposit as collateral, or an existing credit line.
In surety bond insurance, the insurance company provides contractual security under the bond’s terms and conditions. You may avoid using cash margin as collateral.
Here is a simple comparison.
| Factor | Surety bond | Bank guarantee |
| Main cost | Insurance premium | Bank commission and related charges |
| Collateral | May require little or no collateral, depending on terms | May require cash margin or other security |
| Working capital | Can help preserve available cash | May tie up funds or credit limits |
| Pricing | Depends on underwriting, bond type, and tenure. | Depends on bank, risk, amount, and tenure. |
| Best comparison | Premium plus all related charges | Fees plus collateral and financing costs |
How can contractors manage the surety bond cost?
Obtaining a surety bond doesn’t have to strain your business budget. Although you cannot always control all the factors involved in determining the cost of the bond, a few simple things can be done to make sure you come well-prepared with your application process.
1. Keep Your Financial Documents Ready
Before making the application, make sure that all your financial documents, bank details, tax records, and documentation regarding any existing bonds and loans are well arranged. Insurance companies require this documentation to assess your financial standing.
2. Have a Good Project Track Record
In evaluating applications for bond insurance, a previous project track record becomes important. Make sure that you complete the project in due time and in accordance with contractual terms. If you are a new contractor, then make sure to provide information about your team members’ experience and expertise in undertaking such projects.
3. Get a Quote Comparison before Finalizing
It is unwise to accept the first quote you get. Take time to compare quotes based on the premium rate, extent of coverage, any exclusions, and extension rates. Also compare quotations by bond amount and validity period.
4. Determine the Bond Amount and Term
Confirm the required security and the term needed for the bond. This will help you choose the right amount and term and avoid unnecessary costs.
5. Anticipate Any Delays in the Project
Construction projects are not always completed on time, and delays can require you to extend your bond. Hence, stay aware of your project deadlines and talk to your insurer about it.
6. Consider Other Expenses Besides the Premium
Low premiums don’t always mean low cost. Look for other costs like GST, stamp duties, fees, etc. Be aware of all costs involved before making any commitment.
Conclusion
In conclusion, understanding surety bond costs in India helps contractors bid on projects and plan working capital. While indicative premiums range from 0.5% to 3%, the actual cost depends on the bond type, contract duration, financial standing, and other factors. The right surety bond insurance program helps contractors meet contract security requirements without limiting the funds available for business operations. SafeTree offers surety bond insurance plans as an alternative to traditional bank guarantees.
Remember, choosing a good surety bond isn’t just about getting a lower premium. A good surety bond balances the cost of security with the financial flexibility needed to complete projects successfully.
Published by: A2V Insurance Brokers Pvt. Ltd. (SafeTree)
Share this post:
Facebook Twitter LinkedIn WhatsApp